

The Complete Guide to Financial Wellness Programs That Drive Performance and Retention
What actually works, why most programs fail, and how to evaluate any provider, including us.
Financial Stress Is Quietly Undermining Organizational Performance
Your employees bring their money problems to work. Not because they want to, but because financial stress doesn’t wait politely at home. It sits with them in meetings, follows them through the workday, and pulls their attention away from the job in front of them.
The numbers back this up. 59% of employees say financial stress hurts their productivity right now. On average, employees lose 7.3 hours of productivity every week to financial stress, costing U.S. employers an estimated $183 billion annually.
Source: PwC 2026 Employee Financial Wellness Survey; BrightPlan 2024 Wellness Barometer Survey, as cited by SHRM.
Here’s what makes this different from most workforce problems: it’s invisible in your reporting. Financial stress doesn’t show up as a line item. It shows up as turnover you can’t explain, benefits nobody uses, absenteeism that creeps upward, and good people performing below what you know they’re capable of. By the time it’s visible, it’s expensive.
The employers who solve it don’t treat financial wellness as a perk. They treat it as infrastructure.
Coach Hill on the costs most HR leaders never see.
Why Traditional Financial Wellness Programs Fail to Deliver
Most financial wellness programs fail for the same reason most gym memberships fail. Access is not action.
The typical corporate program is a content library: articles, calculators, maybe an app. Employees get a login, HR gets an invoice, and twelve months later usage sits in the single digits. Nobody’s behavior changed because information alone doesn’t change behavior. It never has.
The second failure mode is the one-and-done event. A speaker comes in, the session is great, everyone leaves motivated, and three weeks later the motivation is gone because nothing was built to sustain it. One meal doesn’t make anyone healthy. One seminar doesn’t make anyone financially stable.
53% of employees regret the benefits decisions they made during open enrollment. That’s not a knowledge problem you can fix with a PDF. It’s a behavior and confidence problem, and it needs a different kind of program.
Coach Hill on why benefits education fails when it only happens once a year.
The Shift: From Financial Literacy to Financial Performance
Financial literacy asks: do your employees know things about money? Financial performance asks a better question: do your employees do things with money that make their lives more stable?
That distinction changes how you build a program. Literacy is measured in course completions. Performance is measured in behavior: savings balances that grow, credit scores that climb, benefits that actually get used, stress that actually goes down.
Employers are moving this direction because the stakes are moving. 41% of employers plan to increase financial wellness spending in the next 12 to 24 months (Morgan Stanley, State of the Workplace 2026). The budget is coming. The question is whether it buys another content library or a program built for behavior change.
We believe employees don’t need more information. They need training, the same way athletes need training: structured, repeated, coached, and measured.

The Train Your Money Performance Model™
Every Financial Footwork program is built on one framework, developed over 16+ years and refined inside NFL and NBA organizations, where financial pressure is as real as it gets. It has three pillars.

AWARENESS
Employees can't fix what they can't see. Targeted financial education tailored to your workforce shows people exactly where they stand and what's possible, without judgment and without jargon.
APPLICATION
Knowledge becomes skill through practice. Structured tools, guided exercises, and real-world scenarios move employees from understanding a concept to using it on their next paycheck.
ACCOUNTABILITY
Behavior sticks when someone's watching the follow-through. Reinforcement, goal tracking, and coaching structures sustain the change long after the first session ends.
Unlike passive content libraries or one-and-done presentations, the model integrates all three. That’s the difference between a program employees complete and a program that changes what they do.
What Topics Should a Financial Wellness Program Cover?
The right topics depend on your workforce, but a complete program covers six areas. If a provider’s curriculum is missing more than one of these, ask why.
Budgeting and Cash Flow
The foundation everything else sits on. Employees learn where their money goes and build a system for telling it where to go instead.
Credit and Debt
How credit actually works, how to raise and protect a score, and how to pay down debt with a plan instead of guilt.
Benefits Utilization
The benefits you already pay for only create value when employees understand them. 401(k) matching, HSAs, insurance options, and open enrollment decisions, explained in plain language.
Emergency Savings
The single biggest predictor of financial stress is whether a surprise expense becomes a crisis. Employees build the buffer that keeps a car repair from becoming a payday loan.
Retirement Readiness
Not abstract projections. Practical decisions: how much, which accounts, what the match is worth, and why starting this paycheck beats starting next year.
Fraud and Identity Protection
Scams target the financially stressed. Employees learn to spot fraud, protect their identity, and know who to trust with their money.
Every Financial Footwork program draws from these six areas and goes deeper where your workforce needs it most.
Types of Financial Wellness Programs, Compared
Financial wellness comes in six formats. They’re not interchangeable, and the right answer is usually a combination. Here’s the honest comparison.
| Format | Best For | The Limit |
|---|---|---|
| Keynote | Launching a program, conferences, all-hands events. High energy, high reach. | One session inspires; it doesn't build habits on its own. |
| Workshop | Hands-on skill building for teams. Employees practice, not just listen. | Needs in-person time and works best in smaller groups. |
| Webinar | Remote and distributed teams. Scales to everyone, fits a lunch hour. | Less hands-on than a workshop; engagement depends on the presenter. |
| Seminar | In-person education for larger groups, open enrollment season, company events. | A single session raises awareness more than it changes behavior. |
| Campaign | Actual behavior change. Weekly themes, challenges, and accountability across 4 to 12 weeks. | Requires commitment; a campaign nobody promotes internally underperforms. |
| Platform or app | Reference material between live programming. | This is a library, not a program. Bought alone, usage collapses after week one, which is why we don't sell one. |
The organizations that see lasting change combine formats: a keynote to launch, a campaign to build habits, webinars and workshops to sustain, and benefit videos to reinforce. One format is an event. A combination is a program.
From Framework to Implementation: How the Model Gets Delivered
A framework only matters if it reaches your people. Financial Footwork delivers the Performance Model through live, expert-led programming, scaled to fit your organization:
- Keynote speaking for conferences, leadership events, and program launches
- Financial wellness workshops hands-on, interactive training in 90-minute, half-day, and full-day formats
- Financial wellness webinars live 60-minute virtual sessions for remote and distributed teams
- Financial wellness seminars in-person education for teams and company events
- Financial wellness campaigns structured 4-, 8-, and 12-week initiatives that turn education into habit
- Employee benefit videos custom videos that make your benefits make sense year-round
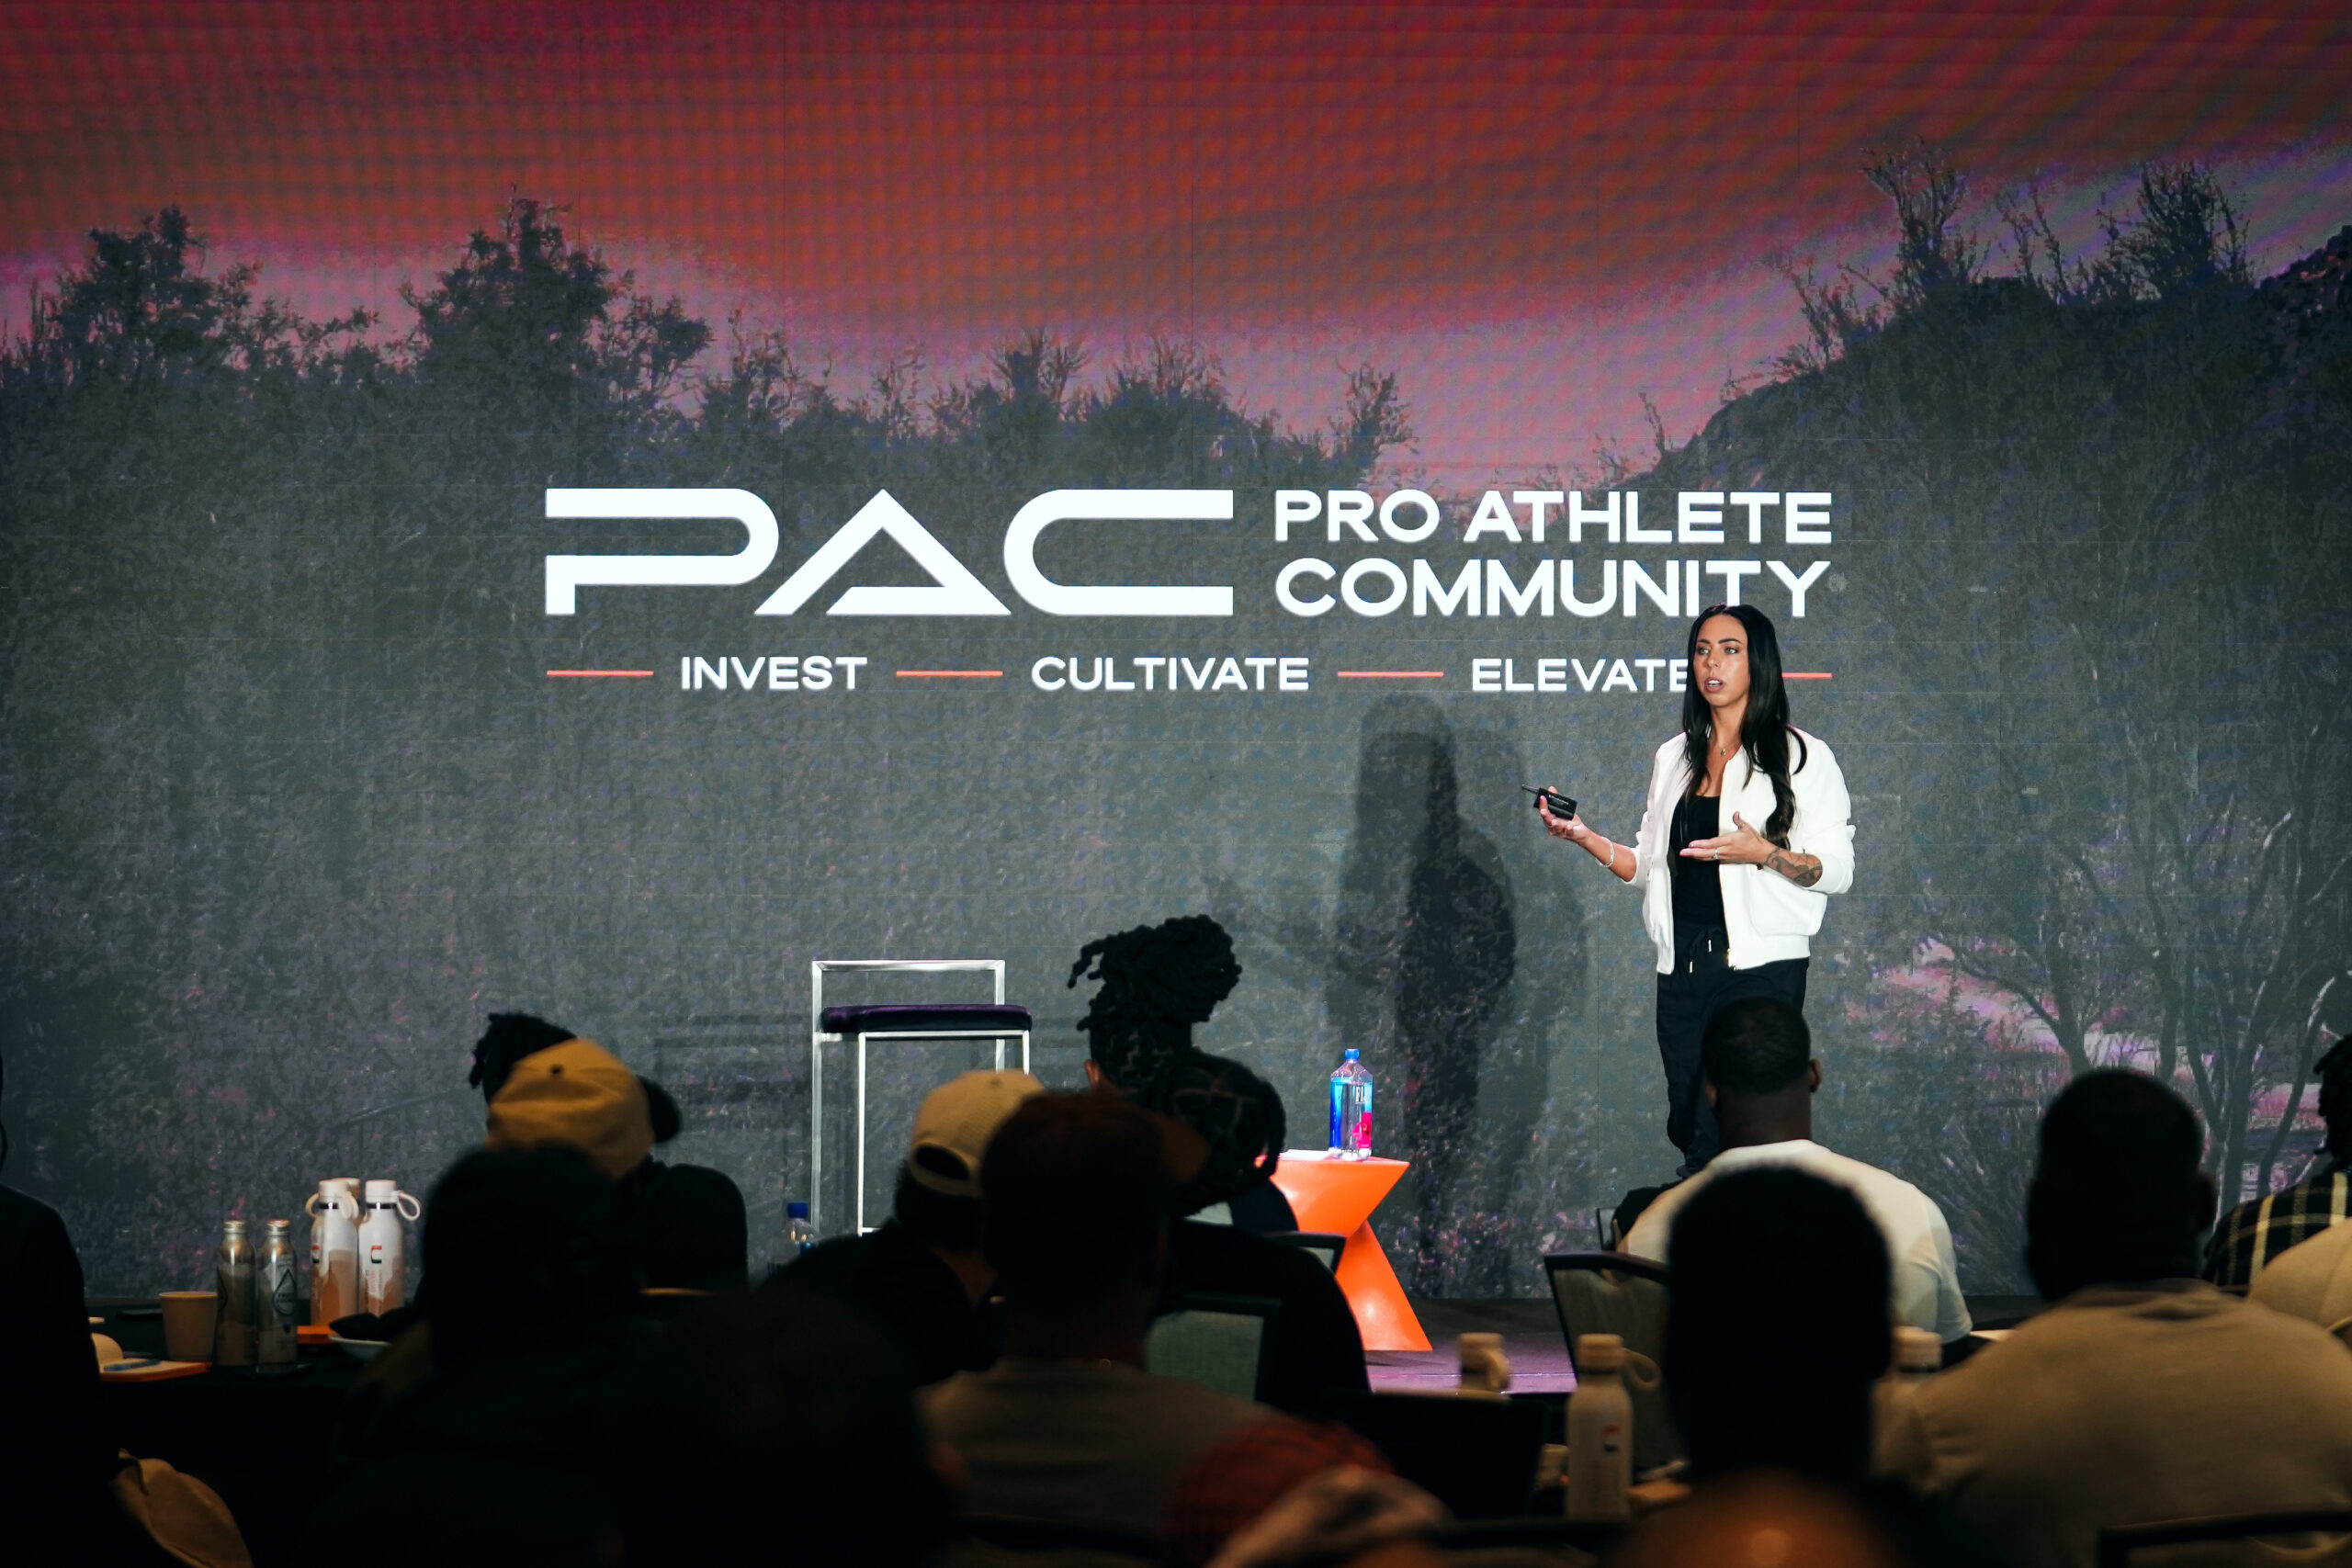
Inside a Financial Footwork live session.
Most organizations don’t start with everything. They start with a keynote or a pilot campaign, see what happens to engagement, and build from there. The model flexes; the framework doesn’t.
For the full picture of how these fit together for your workforce, see our employee financial wellness programs overview.
How to Launch a Financial Wellness Program: A 90-Day Roadmap
You don’t need a year of planning to start. Here’s what the first ninety days look like when we build a program together.
Assess and Design
A strategy call to understand your workforce, your benefits calendar, and your goals. We baseline where your employees are, pick the topics that matter most, and design the program: format, schedule, and how success will be measured. Your team approves the plan. We handle the buildout.
Launch
The program goes live, usually with a kickoff that gets attention: a keynote, a launch webinar, or the first week of a campaign. Employees engage from day one because the content was built for them, not for the broadest possible audience.
Build Momentum and Measure
Weekly programming continues, participation is tracked, and the first measurements come in. By day ninety you have data in hand: who engaged, what changed, and what to scale next. That report is also your business case for whatever comes after.
Ninety days from a strategy call to measurable results. That’s the pace when the program is built for your organization instead of assembled from a template.
Measurable Organizational Outcomes
Results from our multi-year financial wellness program with an NFL organization.
Those numbers come from pre- and post-program measurement, which is the standard every program should meet. At the organizational level, the outcomes employers report are the ones that show up in retention and benefits data: stronger engagement, better benefits utilization, higher 401(k) participation, and fewer of the quiet costs that financial stress creates.
If a provider can’t tell you how they’ll measure change, they’re selling content, not outcomes.
How to Evaluate Any Financial Wellness Program
Whether you talk to us or anyone else, ask these six questions before you sign.
Is it live or is it a library?
Content libraries report logins. Live programs change behavior. Ask what percentage of employees actually engage past week one.
Is it tailored or off the shelf?
Your warehouse team and your executive team have different money problems. One generic curriculum serves neither.
Does it run long enough to build habits?
Behavior change takes weeks of repetition, not one lunch hour. Ask what happens after the first session.
How is impact measured?
Pre- and post-assessments with real reporting, or a satisfaction survey? Only one of those tells you if anything changed.
Who actually teaches?
Ask who stands in front of your employees and what qualifies them to talk about money under pressure.
Is the provider selling anything else?
If the "education" leads to product sales or assets under management, it's marketing. Education should have no strings.
Ready to Strengthen Performance Through Financial Wellness?
Every organization is different. Tell us about yours, and we’ll scope a program around your workforce, your goals, and your budget. We’ll respond within one business day.

FAQs
What should a financial wellness program include?

A complete program combines live education (keynotes, workshops, webinars, or seminars), structured multi-week programming that builds habits, tools for goal setting and accountability, and measurement that shows what changed. If any of those four is missing, expect engagement to fade after launch.
How long does it take to see results?
Engagement shows up immediately; behavior change shows up in weeks. Multi-week campaigns typically measure meaningful movement in savings behavior and financial confidence by the end of the program, with pre- and post-assessments documenting the change.
What does a financial wellness program cost?
It depends on format and scale: a single webinar costs less than a 12-week campaign for a 2,000-person workforce. Most providers, including us, scope programs to your headcount and goals. Be cautious of anything priced per license: that’s usually a content library in disguise.
How do we build the business case for leadership?
Use the productivity math: employees lose an average of 7.3 hours per week to financial stress. Multiply by your headcount and average hourly cost, and the program pays for itself with a fraction of that time recovered. Then commit to measuring outcomes so year two’s case is your own data, not an industry statistic.
Why choose live education over an app?
Apps deliver content. Live education delivers change. Most financial wellness platforms sit unused because information alone doesn’t move behavior. Live, tailored programs with accountability built in are how habits actually form, the same way athletes train.
Disclaimer and Waiver – Financial Footwork, Inc., its owners, officers, directors, employees, subsidiaries, service providers, content providers and agents (referred to as “Financial Footwork”) are not financial or investment advisers and not licensed to sell securities or investments. None of the information provided is intended as investment, tax, accounting or legal advice, as an offer or solicitation of an offer to buy or sell, or as an endorsement, of any company, security, fund, or other offering. The information should not be relied upon for purposes of transacting securities or other investments. Your use of the information contained herein is at your own risk. The content is provided ‘as is’ and without warranties, either expressed or implied. Financial Footwork does not promise or guarantee any income or particular result from your use of the information contained herein. Under no circumstances will Financial Footwork be liable for any loss or damage caused by your reliance on the information contained herein. It is your responsibility to evaluate any information, opinion, advice or other content contained. Please seek the advice of professionals, as appropriate, regarding the evaluation of any specific information, opinion, or other content.